How Much House Can You Afford on a $75,000 Salary in Bloomington?
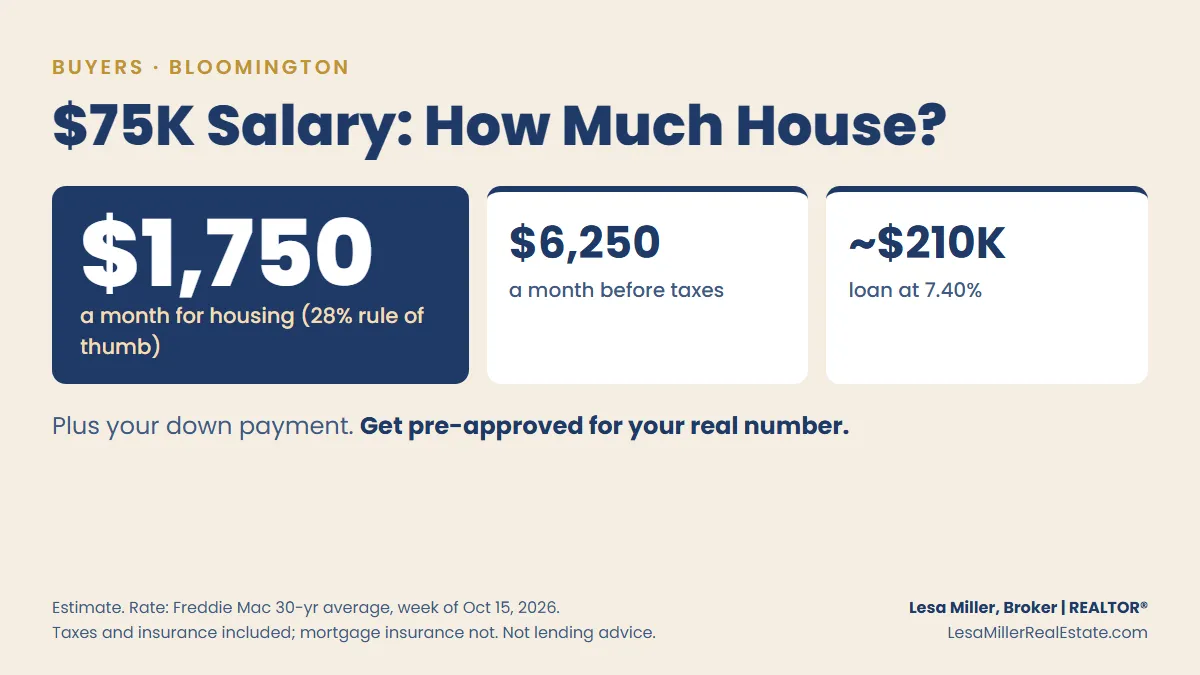
On a $75,000 salary, a common rule of thumb puts your monthly housing budget at about $1,750. At this week's national average rate of 7.40% for a 30-year fixed loan, that budget supports a loan of roughly $210,000, before mortgage insurance. Your down payment goes on top of that. Your own number depends on your debts, your credit and the lender, so treat this as a starting point, not an approval.
Lesa Miller is a REALTOR® and broker in Bloomington, Indiana, who helps first-time and relocating buyers in Bloomington, Ellettsville, Bedford and the surrounding towns. Here's the math I'd walk you through at the kitchen table.
Where does the $1,750 come from?
A $75,000 salary is $6,250 a month before taxes. A common guideline, often called the 28/36 rule, says to keep your housing payment at or under 28% of your gross monthly income. That's $1,750. The housing payment includes principal, interest, property taxes and homeowner's insurance.
It's a rule of thumb, not a law. Some loan programs approve higher ratios, and being approved for more doesn't mean more is comfortable for you.
What does $1,750 a month buy at 7.40%?
Here's an example. It is an estimate, not a quote.
Rate: 7.40%, Freddie Mac's 30-year fixed average for the week of October 15, 2026.
Property taxes: Indiana caps homestead property taxes at 1% of the home's gross assessed value, so I used 1% of the price as a high-side estimate. Many homes pay less, and voter-approved referendums can add to it.
Insurance: I set aside $100 a month as a placeholder. Get a real quote.
With 10% down, that works out to a price of about $233,000: a loan of about $210,000, around $1,455 a month in principal and interest, about $195 a month in taxes and $100 for insurance. With 5% down, it's closer to $222,000.
Under 20% down, most loans add mortgage insurance, which lowers the price a little more. A lender can give you the real figure.
What changes the number?
Your other debts. Car loans, student loans and credit cards count. The "36" in the 28/36 rule means total debt payments at or under 36% of gross income.
The rate. A lower rate stretches the same budget further.
A second income or a bigger down payment.
HOA fees. They come out of the same monthly budget.
My post on What Are Mortgage Rates in Indiana This Week? walks through how the rate moves your payment.
What should you do first?
Talk to a lender and get pre-approved. A pre-approval reads your actual credit, income and debts, so it replaces this estimate with a real number. Pre-Qualified vs. Pre-Approved explains the difference, and the cost of living in Bloomington covers the rest of the monthly picture.
Frequently asked questions
How much house can I afford on $75,000 a year?
Using the 28% guideline, about $1,750 a month for housing. At a 7.40% rate with 10% down, that's roughly a $233,000 price, before mortgage insurance. Your lender's pre-approval gives the real number.
Do property taxes in Indiana have a cap?
Yes. Indiana caps homestead property taxes at 1% of the home's gross assessed value. You need the homestead deduction on file to get the 1% cap.
Is the 28% rule required by lenders?
No. It's a common guideline. Lenders use their own standards, and some loan programs allow higher ratios.
Thinking about buying? Call or text (812) 360-3863, or visit LesaMillerRealEstate.com/Links. Let's start with what fits your budget.
This post is general information, not lending or financial advice. Talk to a lender about your situation.