What Title Insurance Covers When You Buy in Indiana
I have closed homes in Bloomington and Bedford for over twenty years, and title insurance is one of the line items buyers understand the least. It shows up on every closing disclosure, and most people sign off on it without knowing what it pays for.
Here is what that line item covers, what it costs in south-central Indiana, and when it matters most. If you have not sorted out financing yet, the difference between being pre-qualified and pre-approved is the logical starting point before you get this deep into a purchase.
What Does Title Insurance Cover?
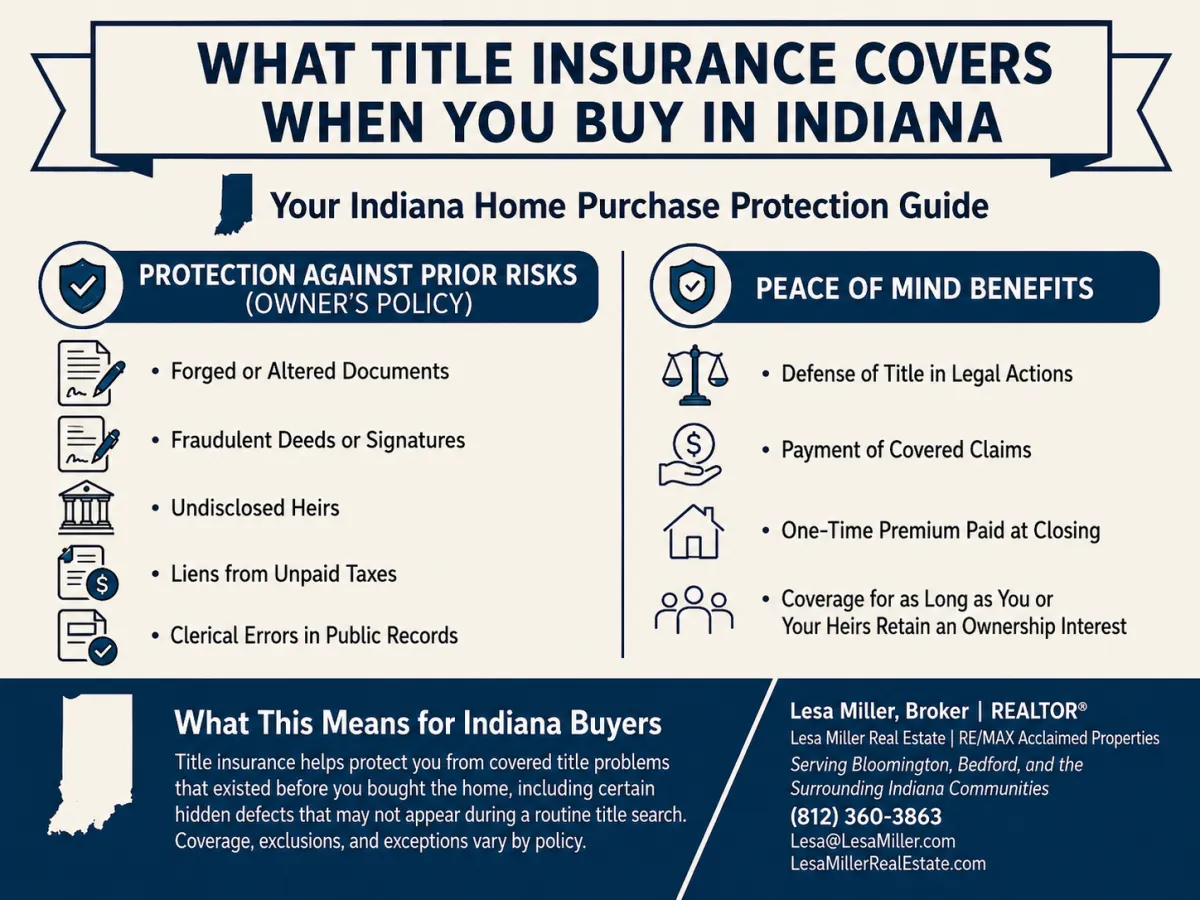
Title insurance protects you against problems in a property's ownership history that a title search did not catch before closing. That includes an old unpaid contractor's lien, a deed with a forged signature somewhere in the chain of ownership, an heir nobody knew existed, or a clerical error at the county recorder's office from decades ago. If one of those surfaces after you own the home, title insurance pays the legal costs to defend your ownership or resolve the claim.
A title search happens before closing and checks the public record for anything that would cloud your ownership going in. Title insurance exists for what that search cannot find: problems that were never recorded in the first place, or mistakes buried in paperwork from long before you were in the picture.
Owner's Policy vs. Lender's Policy
Indiana closings typically involve two separate title policies, and they do not protect the same person.
Lender's policy: required by nearly every mortgage lender. Protects the lender's financial interest in the loan, not you. Coverage amount matches your loan balance and it is a one-time premium paid at closing.
Owner's policy: not required by state law, but you will not find a title company in Bloomington or Bedford willing to close an insured transaction without one in place. Customarily paid for by the seller in Indiana. Protects you directly, in the amount of your purchase price, for as long as you or your heirs own the home.
In practice, that makes the owner's policy close to a given on any insured closing. What is worth knowing is who is paying for it: in Indiana, that is customarily the seller, not the buyer.
What Does Title Insurance Cost in Indiana?
Title insurance is a one-time premium at closing, not a recurring cost like homeowners insurance. Combined owner's and lender's premiums in Indiana generally run about 0.5 to 1 percent of the purchase price, according to Bankrate and Houzeo's Indiana-specific data.
Homes priced $165,000 to $320,000: roughly $480 to $645
Homes priced $345,000 to $545,000: roughly $695 to $895
Homes priced $570,000 to $970,000: roughly $920 to $1,500
Where you land in those ranges depends on your purchase price, your loan amount, and which title company you use. It is one of several figures that shows up in what shows up in your closing costs as a Bloomington or Bedford buyer, alongside your appraisal, origination fee, and prepaid escrow items. Splitting the two policies this way, seller pays the owner's policy, buyer pays the lender's policy, is the customary arrangement in Indiana, though like any closing cost it can be negotiated differently in a specific contract.
Is Title Insurance Required in Indiana?
No state law requires an owner's title policy in Indiana, but that is close to a formality. In my twenty years of closings, I have not seen a title company willing to do an insured closing without an owner's policy in place, whether the buyer is financing or paying cash. If you are financing, your lender also requires its own separate lender's policy as a condition of the loan.
That protection matters most on rural acreage and older homes where deeds have passed through more hands and boundary lines were drawn long before GPS surveys existed. The more complicated a property's history, the more that policy earns its keep.
What Happens If a Title Problem Turns Up After Closing?
If a covered issue surfaces, your title insurer pays for your legal defense and covers the loss up to your policy amount. That might mean fighting a claim from an unknown heir, clearing an old lien that was never released, or correcting a recording error at the courthouse.
What it does not cover is anything you already knew about before closing, or any lien or judgment you create yourself after you own the home. It is protection against the past, not a shield for decisions you make going forward.
If you are working through a purchase in Bloomington, Bedford, or anywhere in south-central Indiana and want the plain-English version of what is in your closing costs, call or text me at (812) 360-3863 or visit LesaMillerRealEstate.com.
Frequently Asked Questions
Do I have to buy title insurance in Indiana?
Indiana does not require an owner's policy by state law, but you will not find a title company willing to do an insured closing without one in place. If you are financing your purchase, your lender also requires its own separate lender's policy as a condition of the loan.
What is the difference between an owner's policy and a lender's policy?
A lender's policy protects the mortgage company's financial interest and is sized to your loan balance. An owner's policy protects you directly, in the amount of your purchase price, for as long as you or your heirs own the home.
Who pays for title insurance in Indiana, the buyer or the seller?
The customary split in Indiana has the seller paying for the owner's policy and the buyer paying for the lender's policy. Like other closing costs, that split can be negotiated differently in a specific contract, but it is the standard arrangement you will see in Bloomington and Bedford.
How much does title insurance cost on a typical Bloomington or Bedford home?
Combined owner's and lender's premiums in Indiana generally run about 0.5 to 1 percent of the purchase price, commonly in the $500 to $900 range on homes priced between $300,000 and $500,000.